 HART PROPERTY
Liv @ MB
A practical review of Liv @ MB for real buyers.
- District: 15
- Region: RCR
- Type: 99-year Leasehold
- Nearest MRT: Katong Park (TEL) - 330m away
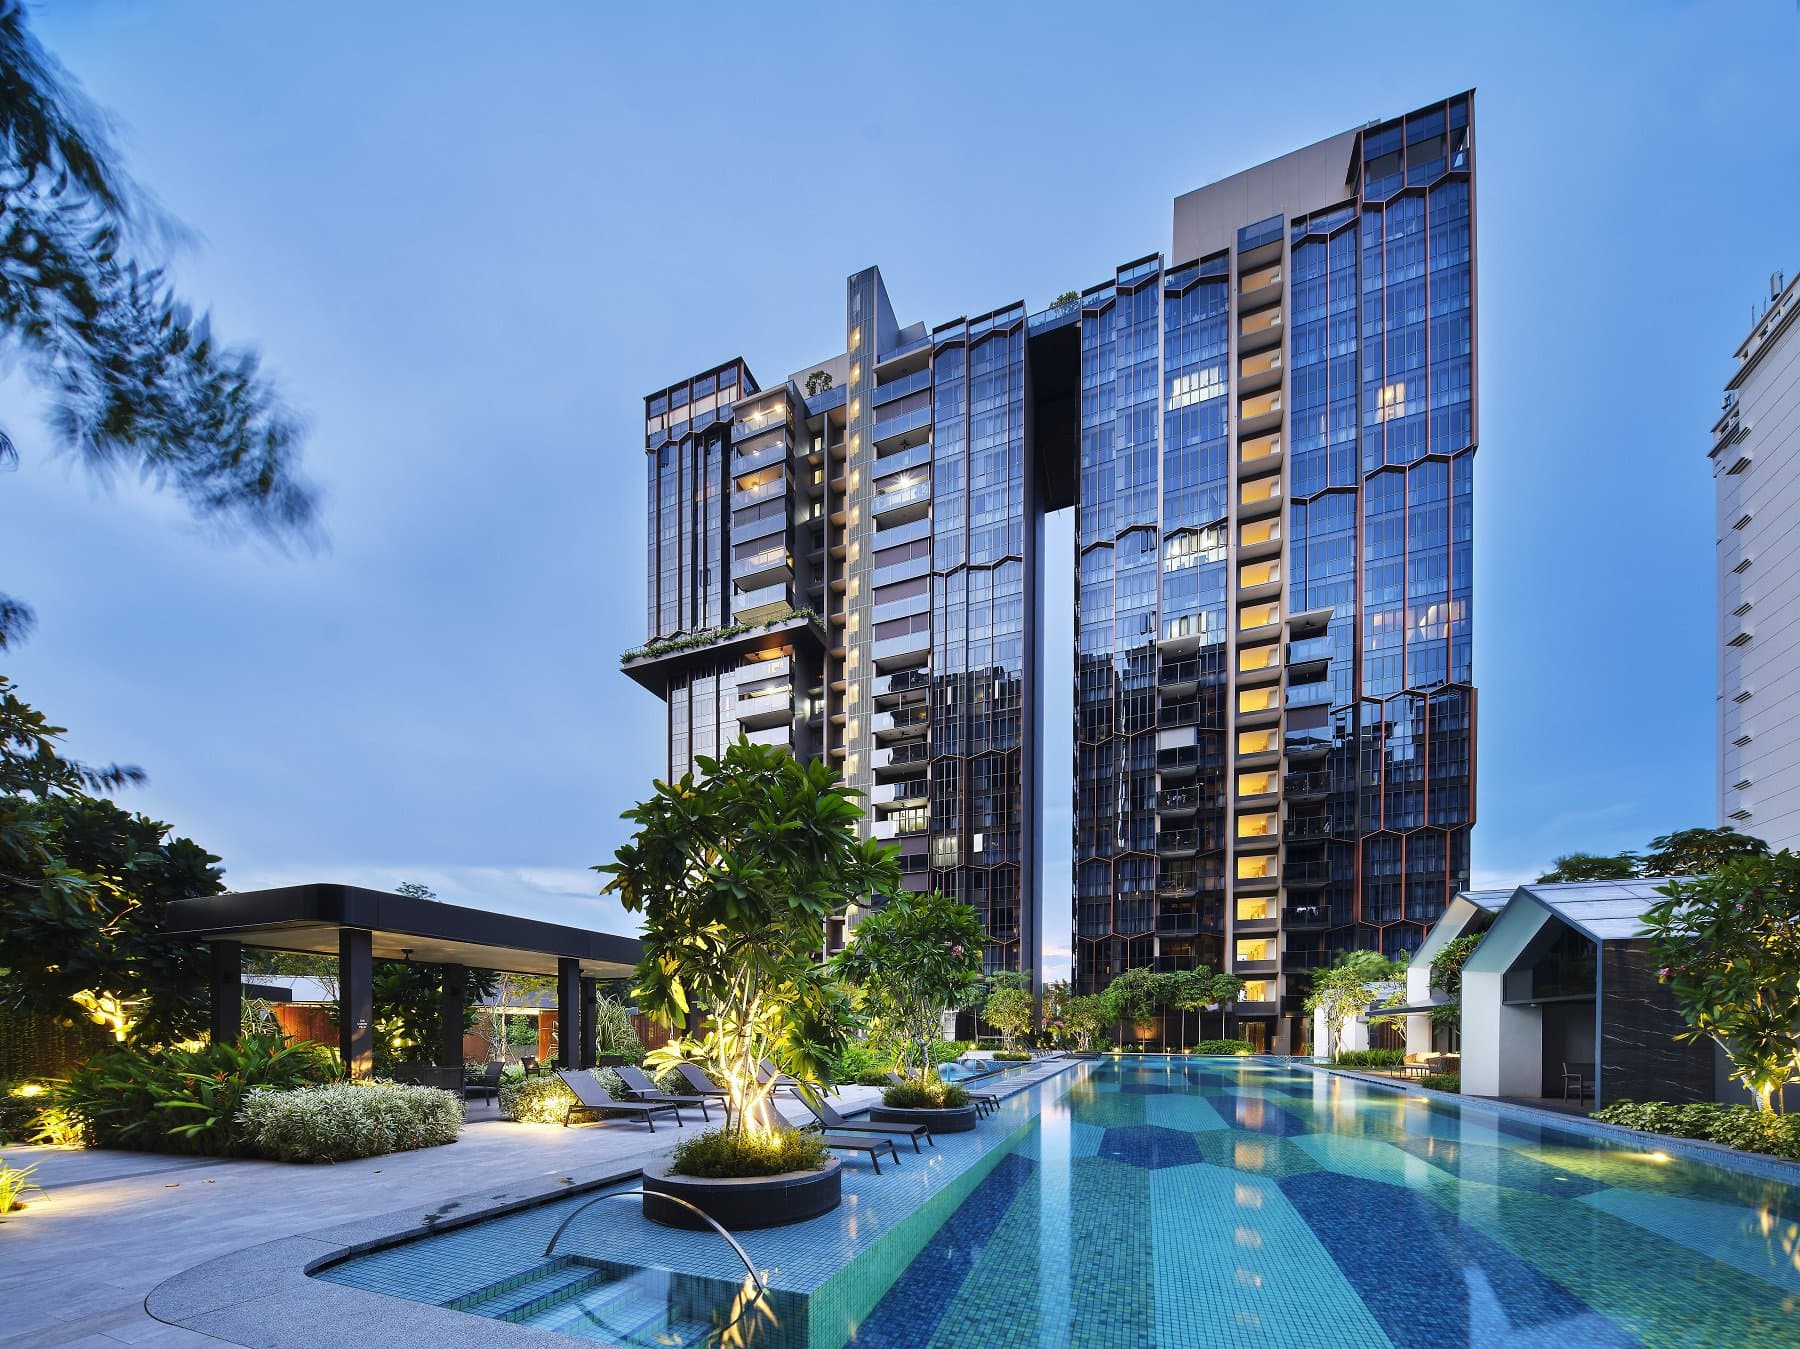
Pricing still has room to grow given relatively few new options in this immediate pocket.
The “product” is not just access — it’s also the luxury feel and tranquility of this pocket, paired with MRT proximity and fast CBD connectivity.
Rental yields are decent (3-4%) because these attributes translate well for both own-stayers and tenants.
Details
Launch prices for each type
Liv@MB was launched May 6th 2022 at $2,200–$2,400 psf, and experienced multiple price increases.
| Type | Typical size range | Launch PSF (basis) | Est. launch quantum (basis) |
|---|---|---|---|
| 1BR | ≈ 495–667 sqft | $2,200–$2,400 psf | ≈ $1.09m–$1.60m |
| 2BR | ≈ 624–1,044 sqft | $2,200–$2,400 psf | ≈ $1.37m–$2.51m |
| 3BR | ≈ 1,119–1,453 sqft | $2,200–$2,400 psf | ≈ $2.46m–$3.49m |
| 4BR | ≈ 1,518–1,668 sqft | $2,200–$2,400 psf | ≈ $3.34m–$4.00m |
Price trend
$PSF trend based on sales transactions since launch.
$2,500–$2,800 psf recent sales, with listings asking $2,600–$3,100 psf. If you entered around the $2,200 to $2,400 range, you saw decent gains.
Nationality by residential status
Breakdown (as provided):
Buyer origin
Comparison with nearby properties (sale & rent)
| Condo | TOP | Tenure | Sale (psf) | Rent (psf) |
|---|---|---|---|---|
| Liv @ MB | 2025 | 99y | $2.5k–$3.1k | $6–$8 |
| Meyer Mansion | 2024 | Freehold | $2.9k–$3.6k | $7–$9 |
| Amber Park | 2023 | Freehold | $2.8k–$3.5k | $7–$9 |
| The Shore Residences | 2013 | 103y | $1.6k–$2.3k | $5.8–$7.0 |
| One Meyer | 2023 | Freehold | $2.9k–$3.4k | $7–$9 |
| Tembusu Grand | 2026 | 99y | $2.2k–$3.3k | $6-$7.5 |
| Fulcrum | 2016 | Freehold | $1.7k–$2.4k | $5.4–$7.3 |
| The Line @ Tanjong Rhu | 2016 | Freehold | $1.9k–$2.4k | $4.5–$6.0 |
| Dakota Residences | 2010 | 99y | $1.9k–$2.1k | $4.7–$5.4 |
| Waterbank at Dakota | 2013 | 99y | $1.4k–$2.8k | $5.8–$7.2 |
Source: URA transaction data. Each point is the average PSF of all transactions in that quarter.
Source: URA rental contract data. Each point is the average rental PSF of all contracts in that quarter.
Analysis and Exit strategy
Pricing
It’s one of the few new launches in the immediate Katong Park / Mountbatten pocket. There was scrutiny about its high launch prices back in 2022, but we need to look again from the lens of the current market.
With OCR new launch pricing hovering around $25xx psf, there’s still some “blind faith” that new launches keep stepping up. Meanwhile, there are subsales in a strong RCR pocket that has historically performed well but is often skipped by investors who only chase the newest OCR supply.
Since TOP, early buyers who entered around $21xx–$22xx psf have (in many cases) crystallised meaningful gains of roughly $300k profit as a common outcome. Recent transactions hovering $25xx–$28xx psf, with listings $26xx–$31xx psf, still leaves room for upside over the next ~4 years if the broader new launch ladder continues to re-anchor.
Rental yields of listings are currently around $6–$8 psf (about 3%–4%), which is a strong profile for RCR if sustained.
One longer-dated tailwind: as part of the wider Kallang revitalisation plans, there are expected to be new Kallang HDBs between Katong Park and Tanjong Rhu.
- King George’s Heights - TOP 2027
- Kallang Horizon & Verandah @ Kallang - TOP March 2028
- Kallang View + Tanjong Rhu Riverfront - TOP 2029
That puts likely upgrader exit/MOP-driven demand in the 2032–2034 window.
Source: ohmyhome.com - PLH flats guide
Lifestyle
Tranquil pocket, ~3 mins walk to MRT, and a hawker centre reportedly being built next to Katong Park MRT. For CBD workers, this is close-to-core accessibility without being in the bustle of the CCR.
Unit mix is roughly half family / half investment. Facilities skew “own-stay friendly” (ground function rooms + rooftop infinity pool / BBQ). BSEL, also known for private residences like Paterson Suites, The Atelier, and Skyline Residences, is a respectable developer and reportedly has been responsive to fixing defects, as well as instituing a good management team. Liv@MB has a mobile app with in-app ticketing system with fast turnaround. Additionally this area is a pet-friendly neighbourhood. At time of writing, move-in tenancy appears to be around 70% with 30% of units rented out.
Layout
All units are north/south facing. Landed/pool views are the better facing stacks. Some layouts are more efficient by skipping balconies, with either an L-shaped entryway for shoes or no entryway straight into the living area.
Larger kitchens + island, plus storage, are uncommon in newer launches — and Liv@MB's 2BR/3BR/4BR sizes (624–1044 sqft; 1119–1453 sqft; 1518–1668 sqft) are bigger than many newer launches. Appliance notes: Bosch double washer/dryer, induction for 2BR, gas for 3BR+; fridge size steps up from 2BR to 3BR+.
7 Decision Points
Disclaimer: This is my assessment and is based on each individual's needs.
Time Horizon
6–8 years
Exit Paths
For Current Owners
If you bought early and are sitting on 4–5% annualised gains, now may be a reasonable exit point. Holding out for more upside before the 6–8 year horizon is possible, but I don't anticipate significantly higher returns in the near term given current market conditions and supply pipeline.
Consider: Is locking in gains now worth more to you than the uncertain upside of waiting?